Strengthening Financial Resilience in a Digital Age
Strengthening Financial Resilience in a Digital Age

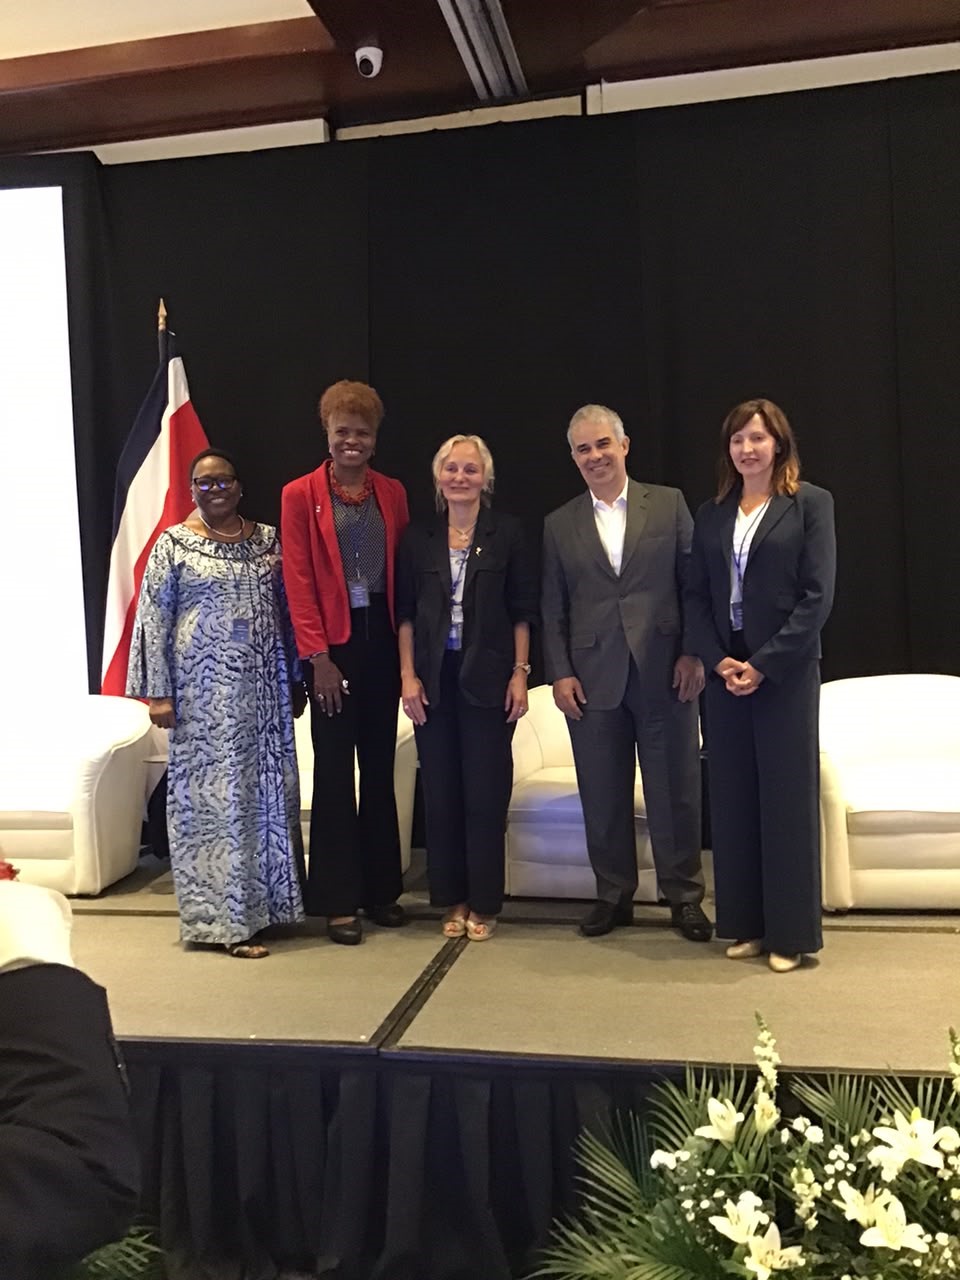
As financial services become increasingly digital, the nature of financial crises is also changing. A cyber incident that begins with a single institution can quickly disrupt interconnected systems, affect access to funds and, if not managed effectively, undermine public confidence. The changing nature of financial services was among the key issues discussed during the 10th Americas Deposit Insurance Forum, held under the theme “Enhancing Deposit Insurance Coverage and Reimbursement: Adapting to Digital Innovation, Emerging Risks, and Operational Challenges.” Against this broader theme, the Forum featured a session on “Crisis Preparedness in the Digital Age: Navigating Operational Resilience and Policy Boundaries for Deposit Insurers,” which brought together experts to examine how deposit insurers can strengthen preparedness and resilience in an increasingly interconnected financial ecosystem. Kenya Deposit Insurance Corporation (KDIC) Chief Executive Officer, Mrs. Hellen Chepkwony, joined the panel, sharing insights on the evolving role of deposit insurers in protecting depositors and supporting financial stability in the digital age.
Mrs. Chepkwony noted that during a cyber incident, where an institution remains viable and can restore customers’ access to their funds, responsibility remains with the institution. However, when a prolonged disruption affects access to deposits, confidence or liquidity, the deposit insurer must become increasingly engaged by monitoring the situation, assessing potential implications and preparing for possible resolution should the institution’s viability deteriorate.
The discussion also highlighted the importance of looking beyond individual institutions. Today’s financial institutions depend on telecommunications networks, cloud services, payment systems, data centres and other third-party providers. A major disruption affecting several of these players at once could test the resilience of the entire financial safety net. For KDIC, this emphasizes the importance of identifying critical dependencies, strengthening alternative arrangements and regularly testing crisis-response capabilities.

The conversation also brought into focus Kenya’s rapidly evolving digital financial landscape. With many Kenyans accessing financial services through mobile platforms, the resilience of the financial system increasingly depends on institutions and service providers that may fall outside the direct mandate of a deposit insurer. Mrs. Chepkwony emphasized that the key consideration is where the underlying funds are held.
The discussion offered an important reminder that financial resilience is no longer solely about what happens within the walls of a bank. It is about how the wider ecosystem works together when disruption occurs. For KDIC, this means continuing to strengthen preparedness, collaboration and coordination with other financial safety-net players and critical service providers.
As Mrs. Chepkwony observed, the real challenge for deposit insurers in the digital age is ensuring that their powers remain operationally effective when a banking crisis is intertwined with disruptions to technology, payments, telecommunications and other critical infrastructure. For KDIC, preparing for that possibility is ultimately about one thing: ensuring that when disruption occurs, depositor protection and financial stability remain at the centre of the response.
Share

-


